
How to Split a Plot in Two: jak podzielić działkę na dwie części Step by Step
Splitting land is the quiet workhorse of small-scale property development, and the question jak podzielić działkę na dwie części sits at the centre of it. Whether the plot is a 0.4-hectare paddock behind a Victorian semi or a 1,200 m² garden strip, learning jak podzielić działkę na dwie części follows the same four-stage spine: title check, planning consent, boundary survey, and registry entry. A single plot worth £180,000 as one title can be worth £230,000 to £260,000 as two separate parcels, which is why owners pursue division before selling rather than after. The costs are modest against that uplift — a chartered surveyor charges roughly £900 to £1,800, legal work adds £600 to £1,200, and registry fees rarely exceed £150. What sinks most projects is not the technical division but sequencing: applying for consent before checking title restrictions, or agreeing a sale before financing is secured.
Check the Title Before You Divide Anything
Every division starts in the land register, not on site. Before a surveyor pegs a single boundary marker, confirm exactly what the title says about easements, restrictive covenants and existing mortgage charges. A drainage easement running diagonally across the middle of a parcel can make a two-way split perfectly legal but commercially worthless.
Polish owners searching jak sprawdzić księgę wieczystą online are doing precisely what UK owners do through the Land Registry portal: pulling the register entry for about £3 and the title plan for another £3. Two documents, six pounds, and you know whether the split is viable before spending anything else on it.
Restrictive covenants are the usual killer. A covenant limiting the land to one dwelling only survives every planning permission you might win, and lifting it through indemnity insurance or a tribunal application costs anywhere from £400 to £6,000. Check for it first, because the entire project timeline hangs on that single line of text.
What an existing mortgage charge changes
If the plot secures a live loan, the lender must consent to releasing part of the security. Most high-street lenders charge £150 to £300 for a partial release and require a fresh valuation of the retained land. Expect four to eight weeks, and budget for the possibility that the lender demands a capital reduction first.
Planning Consent and Surveying the New Boundary
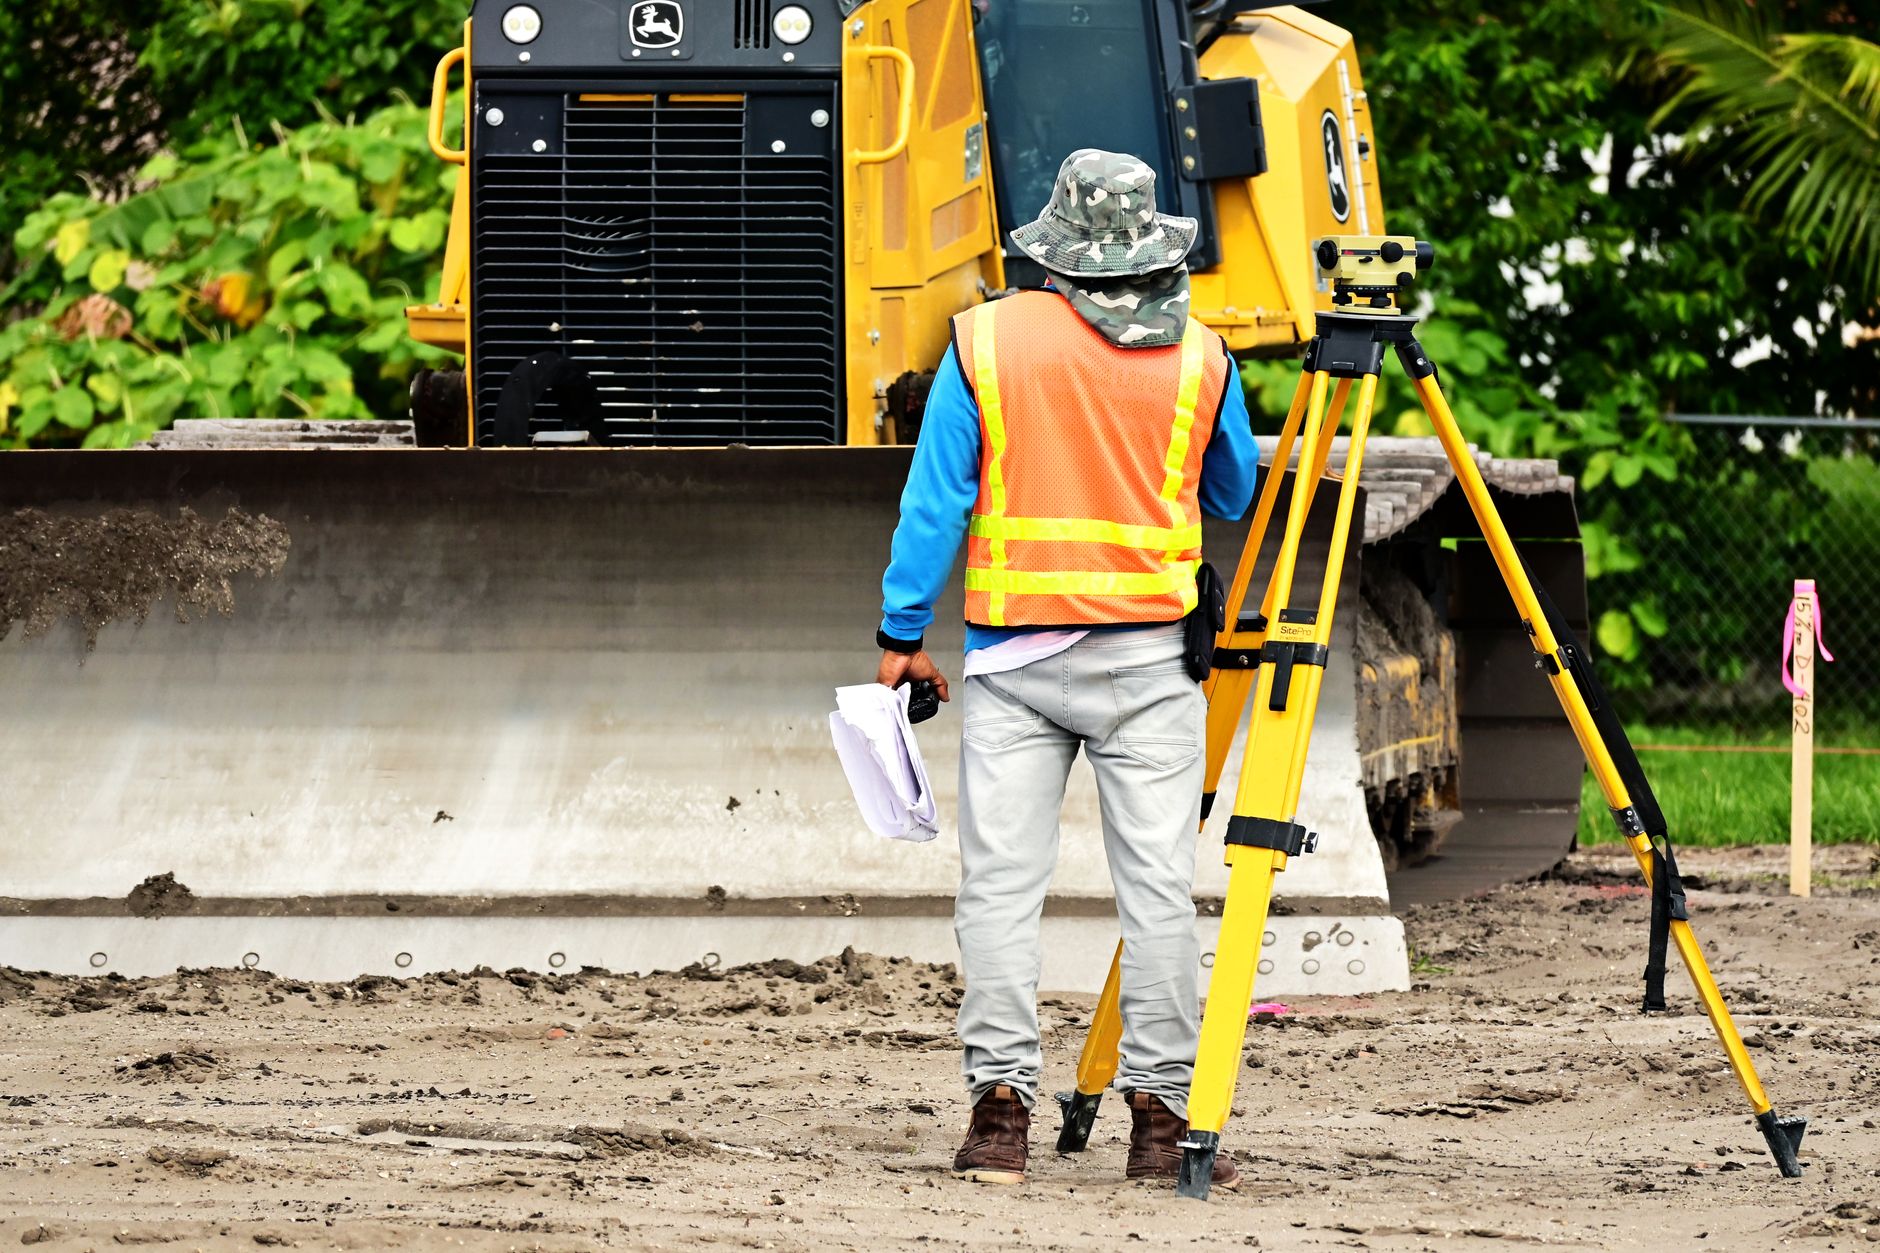
The technical side of jak podzielić działkę na dwie części is a geodetic exercise: a licensed surveyor produces a division plan showing the new boundary line, access arrangements and the area of each parcel. Both resulting plots normally need independent road access and space for utility connections — a plot without frontage is a plot nobody will finance.
Minimum sizes vary by local plan, but 300 to 500 m² per dwelling with frontage of at least 16 to 18 metres is a common threshold. Fail the frontage test and the authority refuses the division outright, regardless of total area. Measure frontage before paying for anything beyond the register download.
Costs stay predictable once you know the sequence. The figures below reflect a straightforward suburban plot with mains services already at the boundary; sloping ground, protected trees or a conservation area designation can comfortably double the survey and consultancy line items.
| Stage | Typical cost (GBP) | Typical duration |
|---|---|---|
| Register entry and title plan | £6 | Same day |
| Boundary and division survey | £900 – £1,800 | 2 – 4 weeks |
| Planning or division application | £280 – £600 | 21 – 60 days |
| Legal and conveyancing work | £600 – £1,200 | 3 – 6 weeks |
| New title registration | £40 – £150 | 2 – 8 weeks |
Decisions on a division application typically land within 21 to 60 days. Refusals usually cite access width or drainage capacity, both fixable with a revised plan. Appeals add three to six months, so a redesigned second submission is almost always faster and cheaper than fighting the original decision head-on.
Financing the Split: Deposits, Affordability and Paperwork
Dividing land is rarely self-funded. Once consent is granted, most owners borrow against the retained plot to pay for servicing works on the new one. Anyone researching zdolność kredytowa jak obliczyć is running the arithmetic an underwriter runs: net income minus committed outgoings, stress-tested at roughly three percentage points above the product rate.
Deposit expectations tighten sharply on land. The logic behind wkład własny do kredytu hipotecznego mirrors UK practice — 10% is standard for a completed home, but bare or partially serviced plots usually demand 25% to 40%. On a £120,000 plot valuation that means £30,000 to £48,000 of your own capital before a single brick moves.
Paperwork volume surprises first-time developers. The checklist behind jakie dokumenty do kredytu hipotecznego stays broadly consistent across lenders:
- Three to six months of payslips and bank statements, or two years of certified accounts if self-employed
- Register entry, title plan and the surveyor’s division drawing
- Planning decision notice or confirmation the division was approved
- Valuation report on both the retained and the newly created parcel
- Proof of deposit source and a schedule of existing credit commitments
How long approval really takes
The honest answer to jak długo trwa decyzja kredytowa is two to six weeks for a standard residential case and eight to twelve where the security is land rather than a finished house. Valuation booking is the bottleneck. Submitting a complete file on day one typically removes around ten days from the average timeline.
Fixed or Variable: Choosing the Rate Structure
Rate structure decides whether the project survives a market that moves against you. The debate framed as kredyt hipoteczny stała czy zmienna stopa reduces to holding period: if you expect to sell the second parcel within 24 months, a variable product with no early repayment charge usually beats a five-year fix by a wide margin.
Reference rates matter more than borrowers assume. Anyone asking co to jest WIRON w kredycie is asking about a transaction-based benchmark replacing older interbank survey averages — the same shift the UK made from LIBOR to SONIA. Transaction-based rates react faster to policy changes, and that speed cuts in both directions on a floating development loan.
Comparison discipline beats brand loyalty. Whoever asks jak wybrać najlepszy kredyt hipoteczny should rank products by total cost across the expected holding period rather than headline rate: arrangement fee, valuation fee, exit charge and interest combined. A 4.60% product with a £999 fee frequently beats a 4.35% product carrying £2,500 in charges over 18 months.
Run the numbers on a £150,000 facility. Over two years, an extra 0.25% of interest costs about £750, while a £1,500 fee gap costs double that on day one. Short horizons reward low fees; long horizons reward low rates. Match the product to the exit plan, never the reverse.
Selling the Second Plot: Contracts, Notary Costs and Repayment
Once the second parcel holds its own title, sale mechanics turn conventional. A preliminary agreement locks the buyer in while conditions are cleared; anyone hunting an umowa przedwstępna sprzedaży mieszkania wzór wants the same protections a UK exchange contract provides — deposit held on account, longstop completion date and defined remedies if either party walks.
Completion charges fall on the buyer in most markets. The question jakie opłaty notarialne przy zakupie mieszkania has a working answer of 0.5% to 1.5% of the price, plus registry fees and tax on the notarial fee itself. On a £110,000 plot that is £700 to £1,900 — quote it accurately in the listing to avoid late renegotiation.
Sale proceeds usually go straight back into the loan. Owners asking ile kosztuje wcześniejsza spłata kredytu should read the product terms closely: early repayment charges commonly run 1% to 3% of the outstanding balance during the first three years, then drop to nil. Clearing £90,000 at a 2% charge costs £1,800 in penalties alone.
Where no charge applies, the strategy behind jak nadpłacać kredyt hipoteczny is simple: overpay in lump sums against capital, then instruct the lender to shorten the term instead of trimming the monthly payment. On a 25-year £200,000 loan, one £20,000 overpayment can remove roughly four years of interest.
How long does the whole plot division process actually take?
Plan for six to twelve months from first register download to two registered titles. The register check takes a day, the boundary survey two to four weeks, and the division decision 21 to 60 days. Legal drafting and the registry entry add another six to fourteen weeks, and lender consent for a partial release of security runs in parallel at four to eight weeks. Delays cluster in two places: waiting for a surveyor during peak construction season, and waiting for a lender valuation slot. Booking the surveyor before the application is submitted and pre-agreeing the release with your lender typically compresses the whole exercise to around seven months.
Is splitting a plot before selling better than selling it whole?
In most cases the split wins, provided the numbers clear a simple test. Total division costs of £2,000 to £4,000 need to be beaten by the price uplift, and on a typical suburban plot the uplift runs £30,000 to £70,000 because two smaller parcels reach a far larger pool of self-builders than one large one. The split loses in three situations: where a restrictive covenant blocks a second dwelling, where the rear parcel has no independent frontage and needs an expensive access strip, and where local plot-size minimums leave one parcel undersized. Knowing jak podzielić działkę na dwie części legally does not make every division profitable — check the covenant and the frontage before committing spend.
What documents does the registry need to create the second title?
The registry expects a defined bundle: the surveyor’s division plan with coordinates and calculated areas, the planning or division decision confirming the split is permitted, the current register entry and title plan for the parent parcel, proof of your ownership, and written lender consent where a mortgage charge sits on the land. Missing lender consent is the single most common rejection reason, followed by a division plan whose areas fail to reconcile with the parent title. Assemble everything before submission, because a returned application restarts the queue rather than pausing it, and that alone can add six to ten weeks to completion.